

Singapore private home prices rise 1.4% in Q3 2026 amid a quieter new launch calendar

Private residential prices in Singapore rose at their fastest pace in nearly two years.
PHOTO: 99.co

Private residential prices in Singapore rose at their fastest pace in nearly two years in Q3 2026. According to the latest data released by the Urban Redevelopment Authority (URA) on 23 October, private home prices rose 1.4 per cent quarter-on-quarter (QOQ), accelerating from 0.5 per cent in Q2.
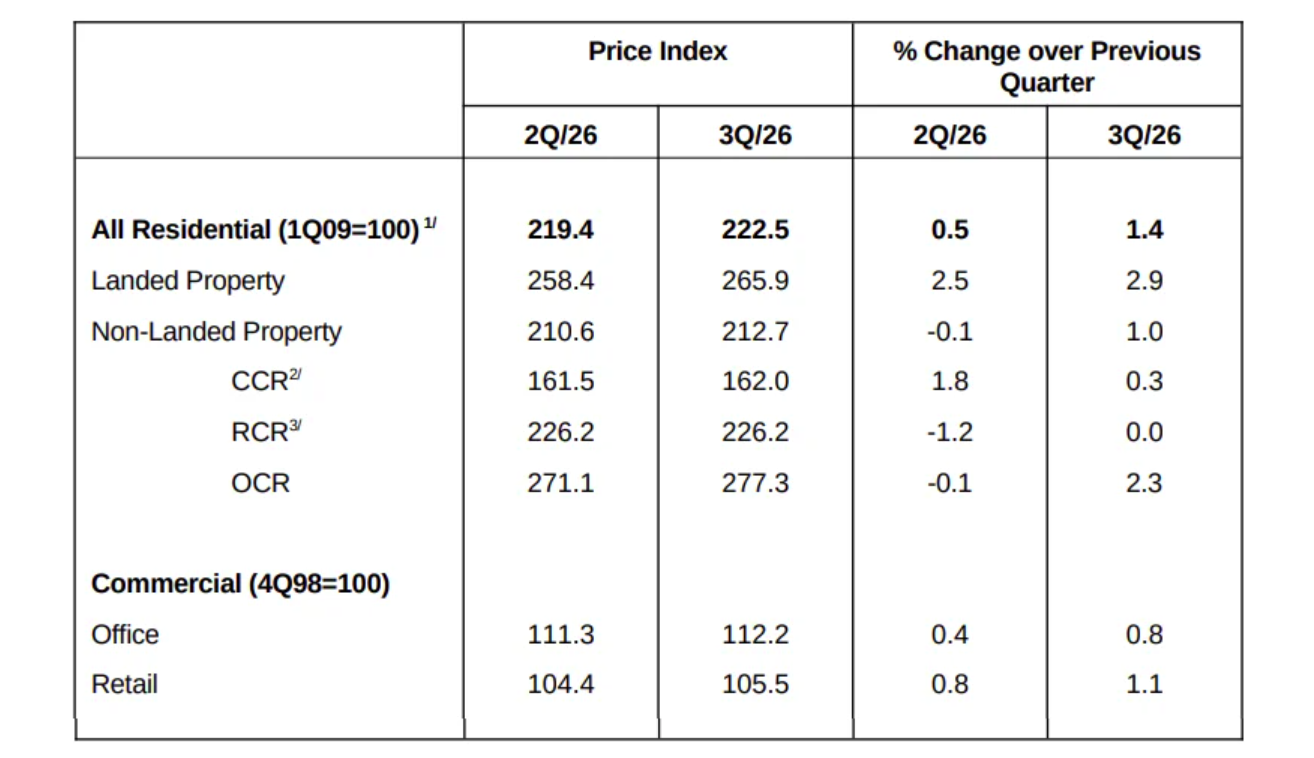
"The latest figure marked an eighth consecutive quarter of private home price growth despite ongoing macroeconomic uncertainty", said Luqman Hakim, Chief Data & Analytics Officer at 99.co. It brings cumulative private home price growth to 2.8 per cent in the first nine months of 2026.
The 1.4 per cent QOQ growth in Q3 2026 was also the strongest quarterly increase since Q4 2024, when prices grew 2.3 per cent.
Landed homes led the gains, with prices rising 2.9 per cent during the quarter, up from 2.5 per cent in Q2. Non-landed private home prices also returned to growth, increasing one per cent after declining 0.1 per cent in the preceding quarter.
Buying momentum, however, has eased. "Transaction volumes fell 16.3 per cent quarter-on-quarter and 30.5 per cent year-on-year, with the sharpest decline in developer sales, partly due to a thinner pipeline of new launches during the quarter," Luqman Hakim explained.
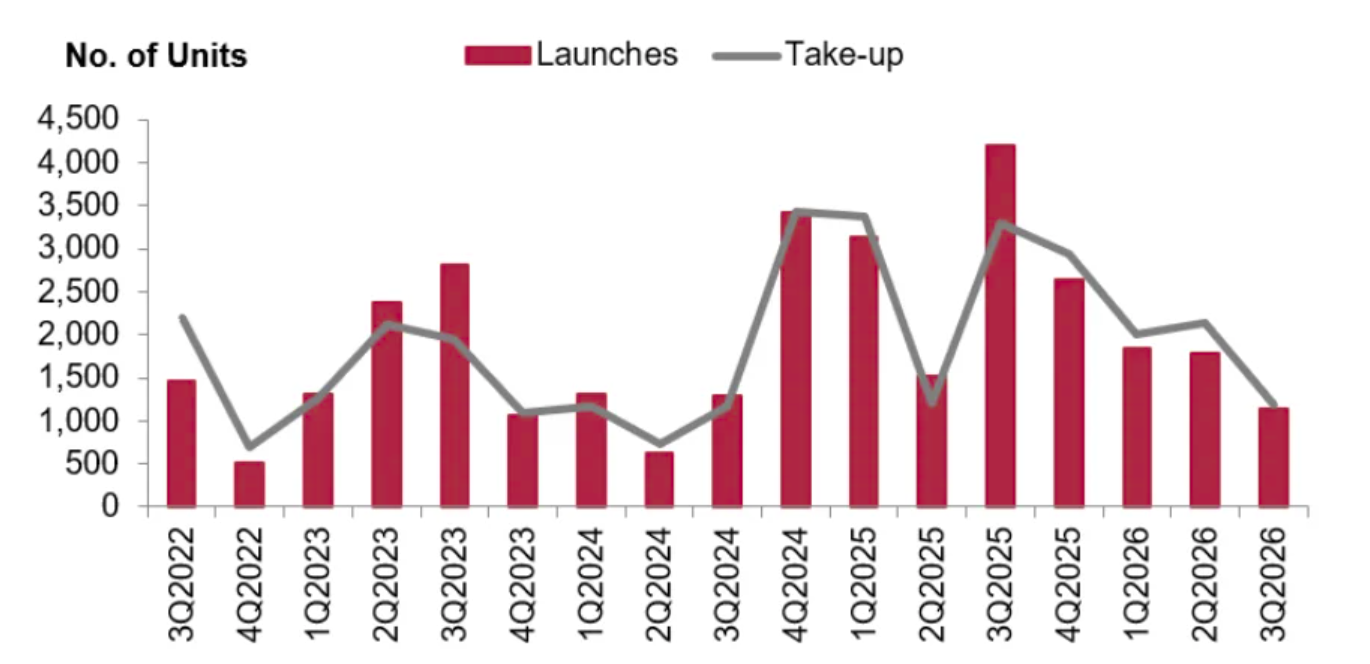
Developers sold 1,183 new private homes, excluding executive condominiums (ECs), in Q3, down 44.7 per cent from 2,141 units in Q2. This was the lowest quarterly sales figure in two years, since Q3 2024.
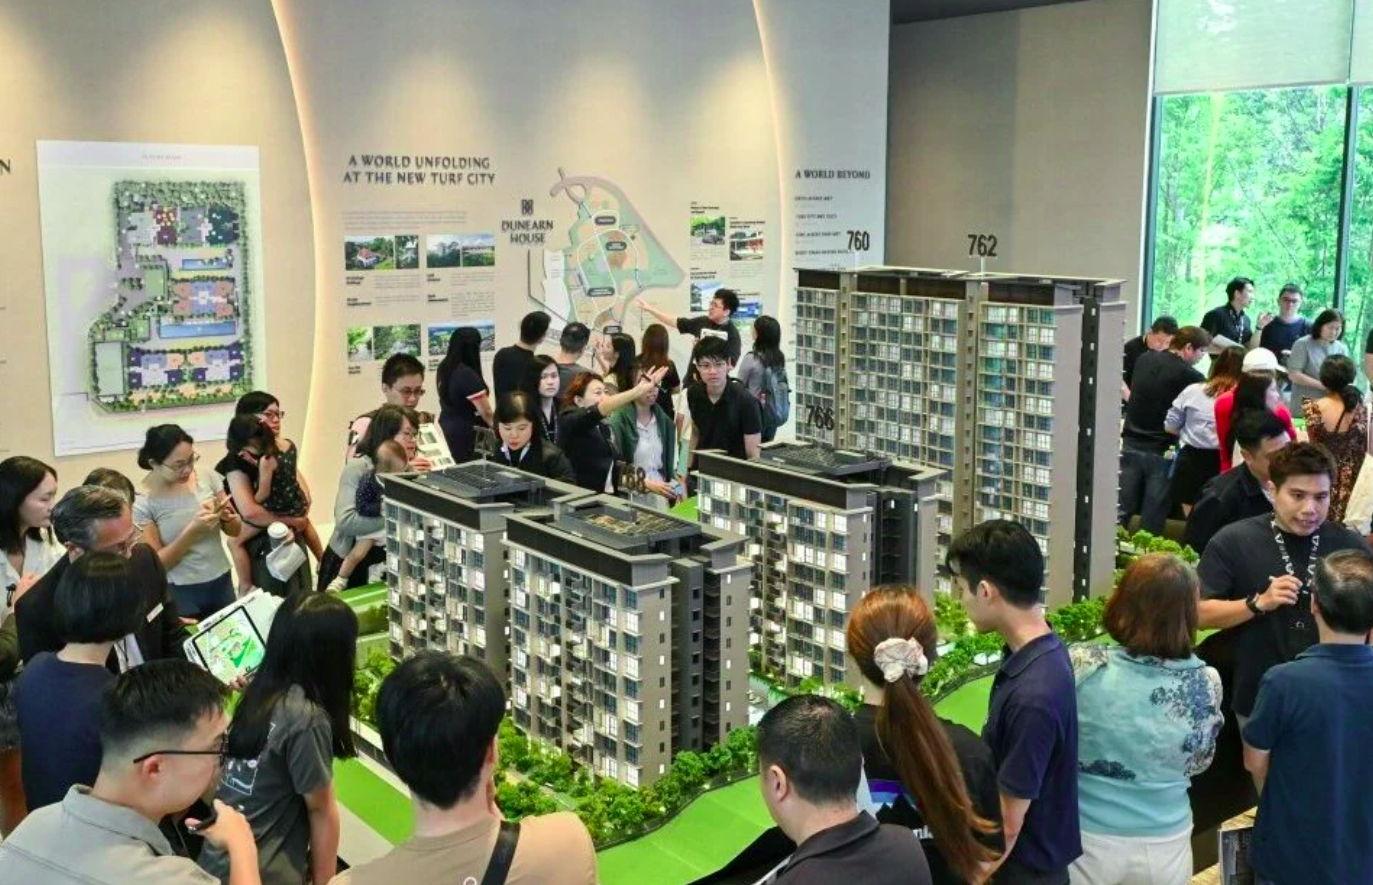
During the quarter, developers launched 1,140 units, compared with 1,783 units in Q2. Lentor Gardens Residences and Dunearn House accounted for much of the new-launch activity during the quarter, while Amberwood at Holland entered the market towards the end of September.
Private resale activity, meanwhile, remained largely stable. A total of 3,801 private homes changed hands in Q3, marginally below the 3,813 units recorded in Q2. With fewer new launches, resales accounted for 73.9 per cent of all private home transactions, up from 62 per cent in the previous quarter.
Overall, 5,146 private residential transactions were recorded during the quarter, down 16.3 per cent QOQ. The shift towards resale homes highlights the role of the secondary market in meeting housing demand when fewer new projects enter the market.
The Outside Central Region (OCR) recorded the strongest price growth among non-landed private homes in Q3 2026.
Prices in the OCR rose 2.3 per cent QOQ, reversing the 0.1 per cent decline in Q2. In comparison, prices in the Core Central Region (CCR) increased by a more modest 0.3 per cent, slowing from 1.8 per cent in the preceding quarter. Prices in the Rest of Central Region (RCR) remained unchanged after falling 1.2 per cent in Q2.
The OCR's performance suggests that demand for suburban condominiums remained firm during the quarter. Resale activity also pointed in the same direction, with over 50 per cent of private resale transactions involving OCR condominiums.
Landed properties were the strongest-performing segment of the private residential market in Q3 2026. Their prices rose 2.9 per cent QOQ, supported by 588 transactions, only slightly below the 592 recorded in Q2.
Higher-value transactions formed a notable part of the market. According to URA Realis caveat data, 52 landed homes sold for at least S$10 million during the quarter. These included a detached house in Dalvey Road that fetched S$56 million on 30 September, the largest caveated landed housing transaction of the quarter.
For the first nine months of 2026, landed home prices rose 5.1 per cent, compared with the 2.8 per cent increase in the overall private residential price index.
Although private home prices strengthened in Q3, affordability continued to influence purchasing decisions. "Buyers are becoming more price-sensitive, with projects at more accessible price points continuing to draw healthy interest," Luqman Hakim added.
At Lentor Gardens Residences, located in the OCR, 77.9 per cent of units sold during the quarter were priced below $2.5 million. The development recorded 304 sales based on caveats lodged during Q3.
Dunearn House in the CCR sold 237 units, of which 46 per cent were priced below $2.5 million. Amberwood at Holland, which offers three- to five-bedroom homes, recorded 24 sales during the quarter, with none priced below $2.5 million.
Lentor Gardens Residences and Dunearn House offered a larger proportion of units within a more accessible overall price range, while Amberwood at Holland's larger family-sized units came with higher purchase prices.
These figures suggest that while buyers remain willing to commit to new private homes, the total purchase price continues to be an important consideration. Developments with units that fall within common budget ranges may therefore be better positioned to attract a broader pool of buyers.
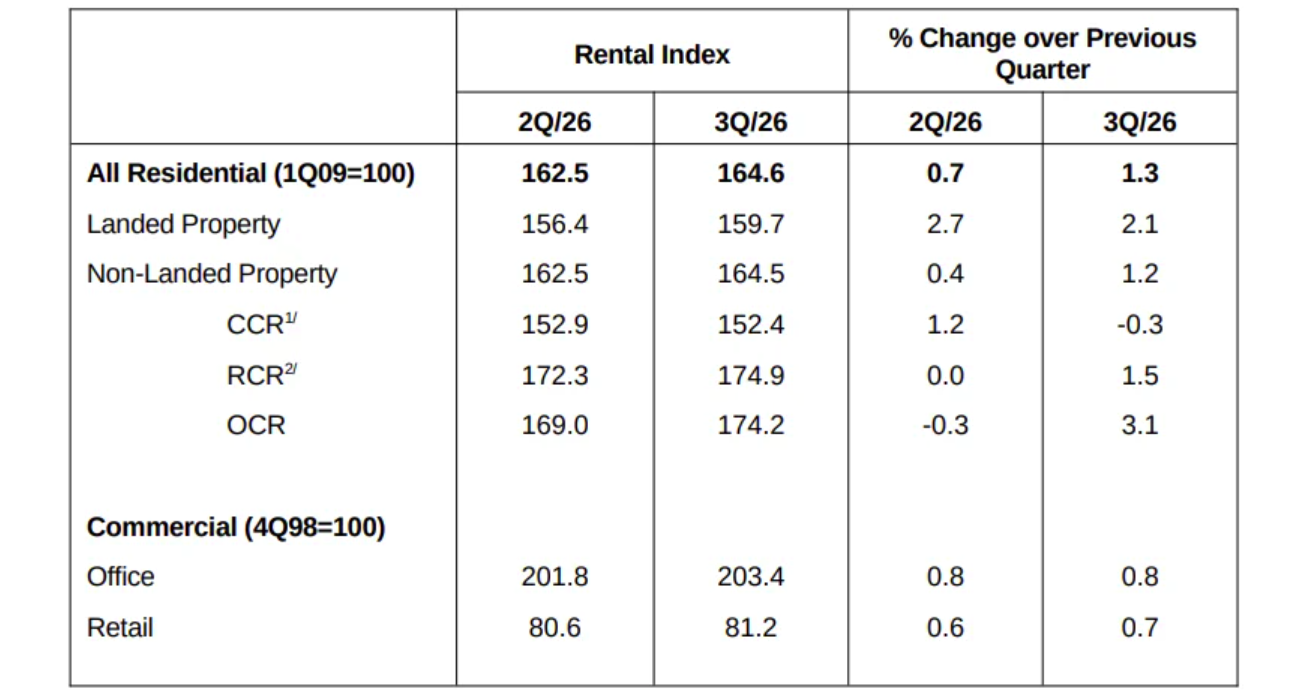
The private residential rental market also strengthened in Q3 2026. The URA rental index rose 1.3 per cent QOQ, accelerating from 0.7 per cent in Q2 and marking the fastest quarterly increase since Q2 2023, when rents climbed 2.8 per cent.
Landed rents increased 2.1 per cent, moderating from the 2.7 per cent growth recorded in the preceding quarter. Non-landed rents rose 1.2 per cent, compared with a 0.4 per cent increase in Q2.
Among non-landed properties, the OCR recorded the strongest rental growth at 3.1 per cent, reversing the 0.3 per cent decline in Q2. Rents in the RCR increased 1.5 per cent, while those in the CCR slipped 0.3 per cent.
Rental demand was reflected in the number of contracts signed. URA Realis data showed that 28,423 rental contracts for private homes, excluding ECs, were recorded in Q3, up 25.6 per cent from 22,635 in Q2. This was the highest quarterly total since records began in 1995.
However, the increase in rents coincided with a rise in completed housing stock. Some 3,559 private homes, excluding ECs, were completed during the quarter, the highest quarterly figure since Q4 2023.
Overall vacancy rose from 6.4 per cent to 7.2 per cent, although occupancy remained relatively healthy at 92.8 per cent.
The combination of higher rents and rising vacancy suggests that the rental market is experiencing stronger demand alongside an expanding supply of completed homes. How rents perform in the coming quarters will depend partly on whether tenant demand can absorb the additional stock.
According to URA, around 32,800 private housing units, including ECs, could be made available for sale over the next one to two years. This forms part of a total supply of 57,200 private residential units expected to be completed over the next few years.
"Looking ahead, prices should remain supported by steady housing demand, low unsold inventory and elevated land and construction costs. That said, heightened buyer price sensitivity and a growing supply pipeline are likely to temper the pace of price growth," Luqman Hakim commented.
The final quarter of 2026 is expected to see a busier launch calendar, with developments such as Thomson Reserve, Lucerne Grand and The Serra Residences among those anticipated to attract attention. Their sales performance could provide a clearer indication of how much demand remains in the primary market as buyers weigh new homes against resale alternatives.
[[nid:748447]]